A monthly budget is not a punishment plan. It is a forecast — an estimate of what will come in, what will go out, and what is left over to push toward longer goals. Most people skip the forecast and then wonder why the destination keeps moving.
The Bureau of Labor Statistics reports that the average U.S. household spends roughly $77,000 per year, but that single number hides enormous variation: housing costs that range from 25% to 50% of income, transportation costs that double in suburban and rural areas, and childcare costs that, in many metros, exceed in-state college tuition. Without a budget, those numbers are abstract. With one, they become decisions.
Women face additional budgeting realities worth naming up front: lower median earnings across most occupations, longer life expectancies (which require larger retirement savings), and a higher likelihood of taking career breaks for caregiving. A budget does not solve those structural issues, but it does turn them from background anxiety into specific line items that can be planned for.
Step 1: Calculate Real After-Tax Income
A budget built on gross income is fiction. The number that matters is the deposit that actually lands in the bank account on payday — after federal, state, Social Security, Medicare, health insurance premiums, and pre-tax retirement contributions.
For a salaried employee, this is the net paycheck multiplied by the number of paychecks per month (two for semi-monthly pay, 2.17 for biweekly pay averaged across a year). For variable income — commissions, tips, freelance work — the safer approach is to use the lowest three months of the past twelve as the planning baseline. Anything above that becomes savings, not lifestyle.
Two paydays a month means 24 paychecks a year. Biweekly pay means 26 paychecks — two “extra” paychecks that, if planned for, can fund vacations, holiday spending, or an annual insurance bill without disrupting the regular monthly rhythm.
Step 2: List Every Fixed Expense
Fixed expenses are the bills that arrive on a predictable schedule for a predictable amount. Pull three months of bank statements and credit card statements and write down every recurring charge:
- Rent or mortgage (principal, interest, taxes, insurance)
- Utilities (electric, gas, water, internet, phone)
- Insurance (health, auto, renters, life, disability)
- Subscriptions (streaming, software, gym, storage, news)
- Loan payments (auto, student, personal, credit card minimums)
- Childcare or tuition
- Recurring memberships and donations
Most people are surprised by the subscription total. A 2023 C+R Research survey found Americans underestimate their monthly subscription spending by an average of $133. Cancelling one $15 service nobody uses adds $180 a year to the savings rate.
Step 3: Estimate Variable Expenses
Variable expenses move month to month: groceries, gas, dining, household goods, clothing, gifts, medical co-pays, pet expenses. The same three months of statements provide the data. Average the three months for each category to get a starting estimate.
Two categories that tend to be underestimated:
- Groceries. USDA’s “moderate cost” food plan estimates roughly $315 per adult per month at home, but that excludes household supplies that often run through the grocery budget.
- Personal care and clothing. Often dismissed as small but compounds to $200-400 per month for many women once haircuts, skincare, cosmetics, work clothing, and dry cleaning are tallied.
Add a 10% buffer to the variable expense total. The buffer covers the month that runs slightly long without breaking the budget.
Step 4: Assign Every Dollar a Job
This is where a list of expenses becomes a budget. Subtract total expenses (fixed plus variable plus buffer) from after-tax income. The remainder gets allocated before the month begins:
- Emergency fund (until it reaches three to six months of expenses)
- Employer 401(k) match (if not already maxed)
- High-interest debt payoff
- Retirement accounts (Roth IRA, traditional IRA, 401(k) beyond the match)
- Sinking funds for known future expenses (car repair, holidays, annual insurance)
- Taxable brokerage investing
A budget where the remainder is left unassigned tends to disappear into discretionary spending by the third week of the month. The fix is to move savings transfers to payday, before the money has a chance to drift.
For readers ready to move savings into invested assets, the article on 3 simple ways to become a successful investor lays out a starting framework.
Step 5: Review Weekly, Recalibrate Monthly
A budget set once and never reviewed is a wish list. The maintenance schedule is simple:
- Weekly (10 minutes). Open the budget, reconcile spending against the plan, and note any category running hot.
- Monthly (30-45 minutes). Compare actual spending to planned spending in every category. Adjust next month’s plan based on what was wrong about this month’s. Move surplus into the savings bucket; cover small overages from the buffer.
The first three months are the hardest because the estimates are usually off by 15-25% in several categories. By month six, most households are within 5% of their plan in every category, and the weekly review takes five minutes.
Choosing a Budget Tool
The right tool is the one that gets used. The options range from free to roughly $100 per year:
- Pen and paper or a simple notebook. Works for people who want minimal friction and do not mind manual entry.
- Spreadsheet (Google Sheets, Excel). Free, infinitely customizable, requires the most setup.
- Budgeting apps (YNAB, Monarch, Copilot, Rocket Money). Auto-import transactions from bank accounts. Subscription cost ranges from $8 to $15 per month. Best for households with many accounts.
- Bank-provided tools. Most major banks now offer basic budgeting features inside their apps at no extra cost. Adequate for simple needs.
Switching tools every six months is itself a budgeting problem. Pick one, commit to it for at least a year, and move on only if it genuinely does not work.
Common Budget Failures and How to Fix Them
Forgetting irregular expenses. Annual insurance premiums, holiday spending, car registration, and tax preparation fees do not show up in any given month but bury the budget when they arrive. Fix: create sinking funds — monthly transfers to a savings account labeled for each known annual expense.
Underestimating wants. A budget that allocates $0 to dining out from a household that historically spends $300 a month on takeout is not a budget; it is a fantasy. Fix: budget for actual behavior first, then reduce gradually.
Treating savings as the leftover. Whatever remains after expenses is almost always zero. Fix: move savings to the top of the budget. Spending fills the rest of the space.
Ignoring partner income. Couples who keep finances entirely separate often miss the household-level view. Fix: even with separate accounts, build a joint budget that shows combined income, joint expenses, and individual discretionary spending.
When the Budget Says No
A working budget will, eventually, deliver a hard answer: the income does not support the lifestyle. There are only four levers — increase income, decrease fixed expenses, decrease variable expenses, or extend the timeline on goals.
The levers in order of typical impact: housing (the biggest fixed expense), transportation (often the second biggest), food (the biggest variable), and discretionary subscriptions. Cutting $5 lattes is a meme, not a strategy. Renegotiating rent, refinancing a car loan, or switching from a $500/month car payment to a $200/month used car is a strategy.
For women considering whether their full financial picture warrants outside help, the perspective in why aren’t more women working with a financial planner is worth reading.
Frequently Asked Questions
How long does it take to set up a monthly budget?
The initial setup, using three months of statements, takes about two hours. Weekly maintenance after that runs five to fifteen minutes. Most people see their first realistic, achievable budget by the end of month three.
What percentage of income should go to each category?
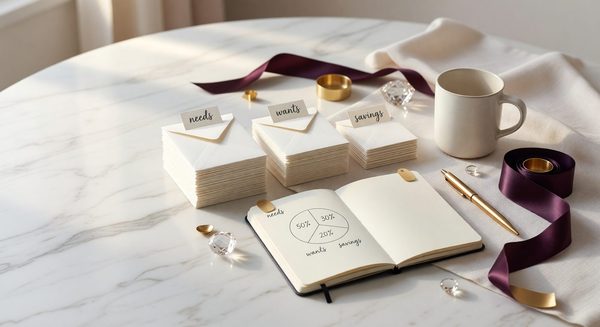
A common starting framework is 50% needs, 30% wants, 20% savings and debt payoff. The percentages shift based on cost of living, debt load, and life stage, but the categories themselves are stable.
Should I budget by paycheck or by month?
Paycheck-based budgeting (assigning each paycheck to specific bills) works well for hourly workers and anyone living close to their means. Monthly budgeting is cleaner for salaried workers with a stable paycheck and a buffer in checking. Both approaches end up at the same place if executed consistently.
How do I budget with a variable income?
Use the lowest three months of the past twelve as the planning baseline. Anything above that goes into savings or a smoothing account that funds lean months. The smoothing account effectively turns variable income into a steady “salary” the budget can plan around.
How do I budget when my partner spends differently?
A joint budget covers joint expenses and savings goals. Each partner gets a personal discretionary allocation — equal in dollars or scaled to income, whichever the couple agrees on — that can be spent without justification. The arrangement removes the most common money fight, which is one partner feeling policed.
Do I need a budget if I’m not in debt?
Yes. A budget for someone without debt is not a recovery plan; it is a wealth-building plan. The same exercise that pays down debt for one household builds an investment portfolio for another. The framework does not change.