Saving money doesn’t usually come from one dramatic change. It comes from a collection of smaller decisions that, when stacked together, make a meaningful difference in your monthly numbers and your long-term financial position.
This list is organized by category so you can skim to what’s most relevant to your situation. Not every strategy fits every life — but even implementing five or six of these consistently tends to move the needle.
Housing (The Biggest Lever)
1. Refinance your mortgage if rates have dropped. Even a half-point reduction on a 30-year mortgage saves tens of thousands over the loan life. Run the break-even math (closing costs ÷ monthly savings) to see if it makes sense.
2. Contest your property tax assessment. Roughly 30–60% of properties are over-assessed, according to the National Taxpayers Union Foundation. The appeals process varies by jurisdiction but is often simpler than expected, and a successful appeal can save hundreds per year.
3. Shop your homeowner’s or renter’s insurance annually. Loyalty doesn’t pay in insurance. Getting competing quotes every 12 months frequently surfaces 10–20% savings with comparable coverage.
4. Lower your thermostat by 2–3 degrees. The Department of Energy estimates that lowering your thermostat 7–10 degrees for 8 hours a day can save up to 10% on heating and cooling bills annually.
5. Switch to LED lighting throughout your home. LED bulbs use 75% less energy than incandescent bulbs and last 25 times longer. The upfront cost typically pays back within a year.
6. Audit your subscriptions. Bank statements reveal the subscriptions that quietly renew. Streaming services, app subscriptions, gym memberships, software, meal kits — total them up. Cancel anything you haven’t actively used in the past 30 days.
Food and Groceries
7. Meal plan before you shop. Planning meals for the week before grocery shopping reduces both food waste and impulse purchases. The average US household wastes $1,500 worth of food per year — most of it from produce that wasn’t part of a plan.
8. Buy staples in bulk — selectively. Unit price math matters here. Bulk buying saves money on non-perishables you use reliably (rice, dried beans, canned goods, paper products) but costs money if the item expires before you use it.
9. Use the store brand default. For most pantry staples, store-brand versions are manufactured by the same suppliers as name brands. The quality difference is minimal; the price difference is typically 20–30%.
10. Cook once, eat multiple times. Batch cooking on weekends — making a large pot of soup, a sheet pan of protein, a grain salad — reduces the temptation to order food on weeknights when time is tight. The cost difference between cooking and delivery can be $10–20 per meal.
11. Pack lunch four days a week instead of five. A single restaurant or deli lunch averages $12–15 in most cities. Packing four days out of five saves roughly $150–200 per month.
12. Drink water. The average American spends $1,200–1,400 per year on bottled beverages including coffee, soft drinks, and bottled water. A reusable water bottle and a home coffee setup eliminates most of that.
Transportation
13. Refinance your auto loan if your credit has improved. If you financed a car when your credit score was lower, refinancing after a year or two of on-time payments often gets you a significantly lower rate.
14. Reduce comprehensive coverage on older vehicles. If your car’s actual cash value (what you’d get from insurance if it were totaled) is less than ten times your annual premium, dropping comprehensive and collision coverage may make financial sense. Keep liability.
15. Combine errands into fewer trips. Combining trips saves fuel and time. This sounds minor but has a real impact — the average driver spends $2,000–3,000 per year on gas, and reducing unnecessary trips makes a dent.
16. Track your tire pressure. Underinflated tires reduce fuel efficiency by up to 0.5% per psi below the recommended pressure. Checking monthly costs nothing.
17. Use public transit or carpool for regular commutes. Even one or two days per week on transit rather than driving reduces fuel, parking, and vehicle wear costs meaningfully.
Financial Accounts and Debt
18. Move your emergency fund to a high-yield savings account. Standard savings accounts at major banks pay 0.01–0.05% interest. High-yield savings accounts at online banks currently pay 4–5% APY on the same FDIC-insured money. On a $10,000 emergency fund, that’s the difference between $5 per year and $400–500 per year.
19. Pay off credit card balances in full every month. Credit card interest rates average 20–24% APR. Carrying a balance is one of the most expensive financial habits you can have. If you’re carrying a balance now, focus on eliminating it before other savings goals.
20. Negotiate your interest rates. Credit card companies will often lower your interest rate if you call and ask, particularly if you’ve been a consistent customer. A 5-minute phone call can reduce your rate by several percentage points.
21. Automate savings before spending. Set up an automatic transfer to savings on the day you’re paid, before money sits in checking. This removes the decision and makes saving the default.
22. Increase your 401(k) contribution by 1% this year. One percentage point typically reduces your take-home pay by less than you expect (because contributions are pre-tax) while significantly boosting your long-term savings. Setting an annual reminder to increase your contribution rate by 1% each year is one of the most powerful compounding moves available.
Shopping and Discretionary Spending
23. Implement a 48-hour rule for non-essential purchases. Wait two days before buying anything over $50 that wasn’t planned. A significant percentage of impulse purchases are reconsidered after the initial urge passes.
24. Unsubscribe from retail emails. Marketing emails exist to create desire for things you weren’t thinking about. Unsubscribing from promotional emails — a one-time five-minute task — reduces that friction.
25. Buy quality secondhand for the right categories. Books, furniture, children’s clothing (which children grow out of quickly), kitchen equipment, and tools are all good candidates for secondhand shopping. Platforms like ThredUp, Facebook Marketplace, and local buy-nothing groups make this easier than it used to be.
26. Use cash-back cards strategically — and pay them off monthly. If you pay your balance in full each month, a good cash-back card on everyday spending effectively gives you 1.5–2% back on purchases you’d make anyway. The catch: this only works if you carry no balance. Credit card interest wipes out cash-back gains quickly.
27. Negotiate one bill per month. Cable, internet, phone, insurance, gym memberships — most of these have negotiating room, especially if you’ve been a customer for a while or can mention a competitor’s rate. One successful negotiation per month, saving even $20–30 each, adds up to real money by year’s end.
Healthcare
28. Use an HSA if you have a high-deductible health plan. Health Savings Accounts offer a triple tax advantage: contributions are pre-tax, growth is tax-free, and withdrawals for qualified medical expenses are tax-free. If you’re eligible, maxing an HSA ($4,150 for individuals, $8,300 for families in 2024) is one of the most efficient savings vehicles available.
29. Shop for generic prescriptions. Generic medications are chemically identical to brand-name versions and typically cost 80–85% less. Ask your doctor or pharmacist whether a generic is available when a new medication is prescribed.
30. Use in-network providers and urgent care instead of emergency rooms for non-emergencies. Emergency room visits for conditions that could be treated at an urgent care clinic average $1,500–2,000 before insurance — versus $100–200 at urgent care. Understanding your insurance network before you need care saves significant money.
The Meta-Strategy
31. Measure your net worth quarterly. You don’t improve what you don’t track. Setting up a simple spreadsheet — assets minus liabilities — and updating it every three months creates a feedback loop. Watching net worth grow, even slowly, reinforces the habits that are working and makes the tradeoffs feel worth it.
The 31 items above aren’t meant to be implemented all at once. Pick three or four that fit your current situation and start there. Add more over time as the first habits become automatic.
Saving money, at its core, is about creating margin — space between what comes in and what goes out. That margin is what makes financial goals possible.
Frequently Asked Questions
How much should I be saving each month?
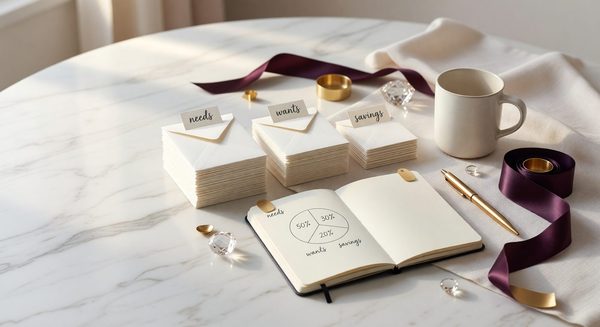
A common benchmark is the 50/30/20 rule: 50% of take-home income toward needs, 30% toward wants, and 20% toward savings and debt repayment. That said, the right savings rate depends on your age, income, debt level, and goals. Someone starting to save in their 30s may need to save 25–30% to catch up. Someone with significant debt may prioritize debt repayment over investing. The most important starting point is any savings rate above zero.
What’s the fastest way to save a significant amount of money?
The fastest single lever is usually housing — moving to a less expensive area, getting a roommate, or downsizing. After that, reducing two or three large recurring expenses (car payment, subscriptions, dining out) typically has more impact than cutting many small ones. The 80/20 principle applies: most of your potential savings are in a handful of categories.
Should I save money or pay off debt first?
If you have high-interest debt (credit cards, personal loans above 10%), prioritize paying it off before aggressive saving beyond a small emergency fund. The math is simple: paying off 22% APR credit card debt is equivalent to a guaranteed 22% return on investment. Once high-interest debt is gone, redirect that payment toward savings and investments.
How do I save money on a low income?
With a tight income, the most impactful moves are usually: capturing any employer 401(k) match (free money), moving savings to a high-yield account, reducing food costs through meal planning, and eliminating any subscription you don’t actively use. Even $25–50 per month saved consistently builds into something meaningful over years. The habits matter as much as the amount.
Is it worth using budgeting apps?
For many people, yes — particularly at the beginning. Apps like YNAB (You Need a Budget) or free options like Mint or Personal Capital help make the abstract concrete. Seeing where money actually goes, rather than where you think it goes, is often the most clarifying financial exercise a person can do. The app itself matters less than the practice of tracking.